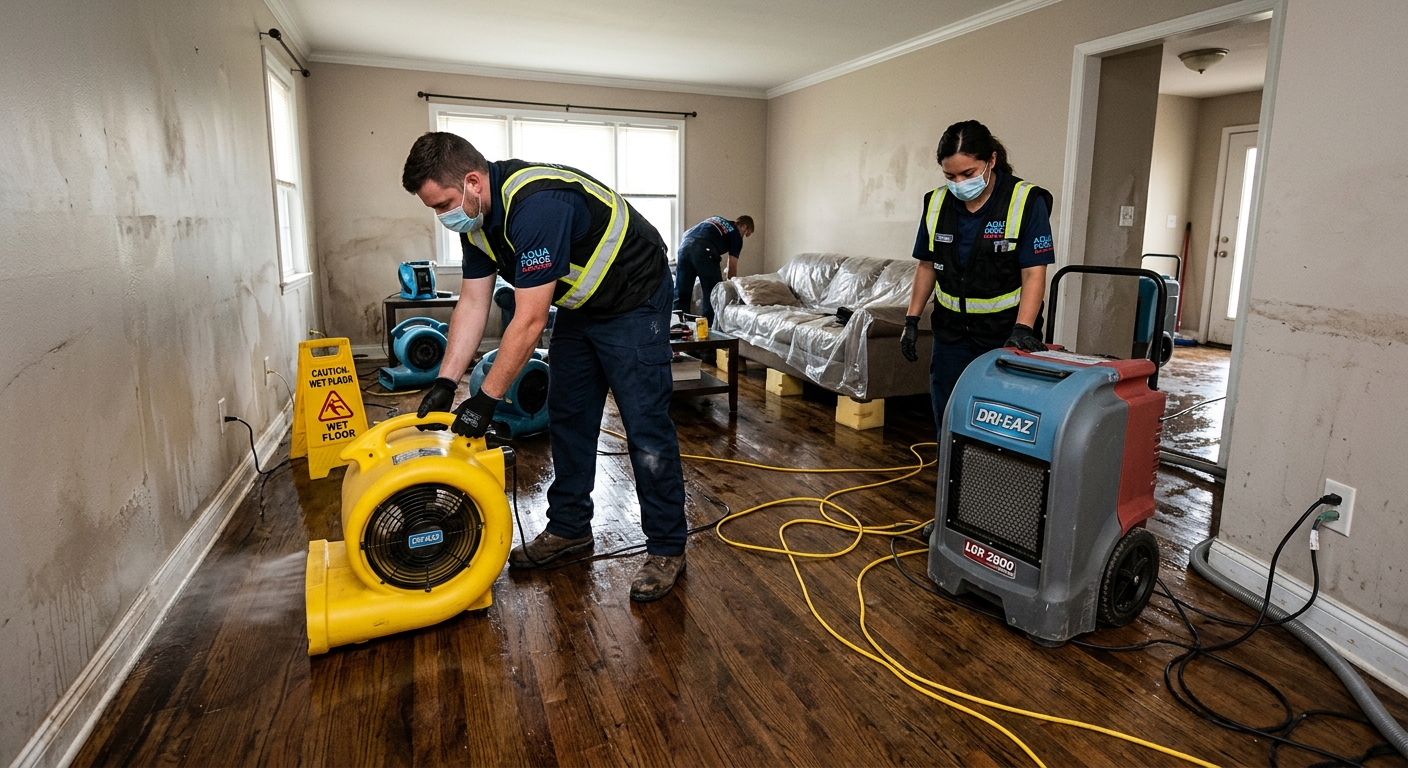
water damage restoration costs in Springfield — 2026
If you are dealing with a water emergency in Springfield right now, knowing real costs helps. Montgomery County has seen surging claims because more than 80% of homes are owner-occupied, with most built before 1980 (U.S. Census Bureau, ACS 2024). That same era’s post‑1945 suburban boom brought copper supply lines to nearly every tract house, and many are now hidden behind finished drywall—making small leaks hard to detect until flooring or finished basements show visible water damage. With full basements standard in Springfield’s housing stock, losses here often mean a bigger footprint, not just a wet corner. Below are 2026 price ranges you can expect for a typical local restoration scenario:
| Service |
What it covers |
Typical duration |
Price range |
| Water extraction + emergency drying (Cat 1) |
extraction, air movers, LGR dehumidifiers, daily moisture monitoring |
3–5 days |
$1,350–$8,500 |
| Structural drying only (post-extraction) |
drying to standard after water is already out |
3–5 days |
$1,150–$8,000 |
| Mold remediation with containment |
containment, HEPA filtration, removal, antimicrobial, clearance test |
3–7 days |
$1,700–$12,000 |
| Sewage backup cleanup (Cat 3) |
biohazard protocol, disposal of porous materials, disinfection |
2–5 days |
$2,800–$13,500 |
| Emergency board-up / tarping |
stop further water entry, secure the structure |
same day |
$350–$900 |
Estimates for a typical Springfield home. Category, affected area and how long the water sat move these figures more than anything else.
What a Pennsylvania restoration contractor must actually hold
Pennsylvania does not issue a state license for water damage restoration or mold remediation; anybody can buy a magnet and print business cards. What matters is the firm’s experience, required insurance, and (if insurance is paying) that they follow IICRC standards—especially S500 for water and S520 for mold work. Always ask to see the lead technician’s IICRC card before saying yes to any work.
If a contract is over $500, the contractor must be registered as a Home Improvement Contractor (HIC) with the Pennsylvania Office of Attorney General. You can verify registration online and should also check that any company claiming employees carries workers' compensation, which you can confirm in the WCAIS system. For jobs in homes built before 1978, companies disturbing paint or finishes must show current EPA Lead RRP credentials.
Permits are not triggered by basic water extraction or like-for-like material replacement (for example, carpeting). But expect to need a municipal permit in Norristown for reconstruction when significant structural repairs follow severe Category 3 (sewage) losses.
Do not allow crews to begin extraction or demolition until you have a clear written agreement in hand. This should spell out your scope of work, pricing or how costs are calculated, the contractor’s HIC number, and your right to a 3-day cancellation as provided by state law. If insurance is involved, make sure you have a signed work authorization but never sign a blank or open-ended contract.
Documenting and recovering contents in Springfield
Most Springfield homeowners, facing a water or sewer loss, focus on the soaked rooms and underestimate the challenge of handling their contents claim. Your policy likely separates coverage for the structure—walls, floors, plumbing—from your contents: furniture, electronics, clothing, kitchen goods, family keepsakes. Restoration contractors offer pack-out services, which means inventorying, photographing, then boxing and moving affected belongings to an off-site facility for cleaning and storage. This step is crucial, not just for salvage, but for insurance documentation.
Before any crew starts moving or removing items, take clear, dated photos in each room—wide angle and close-ups—to prove condition and quantity. Insist the contractor maintain an inventory with serial numbers where possible. After a Category 3 loss (sewage), upholstered furniture, mattresses, and particleboard furniture are almost always considered beyond safe salvage due to biohazard—list these for total loss and do not spend money attempting restoration. Hardwood furniture, electronics, some area rugs, and dishes are often cleanable, especially after Category 1 clean-water events.
Don’t be afraid to ask if pack-out is needed for minor leaks; for limited, isolated water damage, a simple drying-in-place approach may keep costs down and speed your return to normal.
After the repair: hardening the house
Once restoration is finished, a few targeted upgrades make your Springfield home much more resilient. Start with the simplest: swap out old braided washer hoses and water heater supply lines for burst-resistant types—usually under $150–$300 installed. Next, consider an automatic water shutoff valve (with leak detection sensors) for $800–$2,000; this device will shut your main if a leak is detected and is particularly sensible if you travel. Installing leak sensors under major appliances, beneath kitchen sinks, and near your water heater costs little ($60–$250 per unit for WiFi-connected). For basements (standard here), a sump pump with battery backup runs $650–$1,800.
If your property has any history of sewer backup—especially if you’re near aging lines or low-lying areas—a backflow valve is a solid investment at $650–$1,500, but only if the local system is combined/separated as in Norristown. A drain pan under your water heater, piped to a floor drain, rarely costs more than $150–$400 installed. Full-house pipe replacement is not usually cost-effective unless your copper lines are already failing repeatedly.
Given the 30-inch frost depth and the local winter minimum design temperature of 14°F, the most effective anti-freeze strategy remains insulation and shutting off/bleeding outside water lines. Only invest in the bigger-ticket upgrades if your home has had repeated issues or your insurer requires them.
Springfield's housing and its water damage profile
In Springfield and the surrounding Montgomery County townships, nearly 83% of homes were built before 1980, a statistic that shapes both water loss frequency and recovery scope (U.S. Census Bureau, ACS 2024). Most homes from this post‑WWII tract era feature copper supply lines, many of which are now past their rated lifespan. First signs of trouble may not appear until hardwood floors cup or drywall seams swell.
Drywall dominates most basements and finished spaces, making demolition and drying faster and less labor-intensive than traditional lath-and-plaster construction but more challenging if water seeps behind vapor barriers. Cast iron is common in main drains for pre-1970s homes, but many laterals were switched to PVC in the last few decades. Cast iron can slow a sewer backup’s spread but is more difficult to open and clean.
Full basements are the norm thanks to the area’s building traditions. Where a finished basement gets wet, it is far more space per loss—up to triple what you'd face in a slab-on-grade ranch—so both water extraction and drying gear will be in place longer, and insurance adjusters will look for hidden moisture in walls and built-ins.
Overall, Springfield’s housing is neither especially high-risk nor immune; it’s the quiet, slow supply line leak behind decades-old drywall that owners miss until there’s a smell or buckling underfoot.
Springfield's flood exposure and what it means for coverage
Springfield’s risk profile includes real flood exposure thanks to the Schuylkill River and Wissahickon Creek, both named sources where high water can affect basements and first floors. If your address falls in a mapped FEMA flood zone (usually designated on your mortgage or real estate disclosures), your standard homeowner’s policy does not cover water that enters from the ground up or overland storm runoff. Flood coverage is purchased separately, nearly always as a National Flood Insurance Program (NFIP) policy, and comes with a waiting period—typically 30 days—so buying it “just in time” when flood warnings come up isn't an option.
After a big storm, a finished basement with six inches of water looks the same whether it came from a burst pipe or the creek overrunning its banks. But to your adjuster, only the “sudden and accidental” plumbing loss is covered by a basic homeowners policy. Flood water—from overland or river rise—is not. For Springfield, this isn’t a remote technicality; hundreds of homes along creek-adjacent streets have discovered this gap the hard way. If you’re unsure, check your address against FEMA’s map and don’t assume any restoration contractor will know your policy specifics—many do not.
The bottom line: coverage depends on the water’s point of entry and source, not the damage or cleanup needed. Don’t neglect flood insurance even if your property sits a few blocks above the obvious “danger zone.”
Hiring under pressure in Springfield
When water is pouring into your Springfield home, you don’t have time to “get three quotes over a week.” Montgomery County is a saturated restoration market, with major regional operators and local franchises able to send a crew within an hour, even on a busy day. That speed is good, but it also means—not everyone with a rapid response is playing by the same rules.
Before anyone sets foot in your house, confirm three things by phone: 1) They are registered as a Pennsylvania Home Improvement Contractor (HIC); 2) They can provide a certificate of liability insurance and proof of workers' compensation via WCAIS; 3) The company sends IICRC-certified technicians, and the person arriving can show their own card.
Once the truck is in your driveway but before equipment rolls off, have these three documents in hand: Your contract including HIC number and cancellation rights, a clear work authorization (not blank), and a written scope or at least the rate sheet for emergency services.
- Confirm HIC registration online (or ask for the number).
- Check photo ID of the lead tech and IICRC card.
- Get a certificate of insurance naming you as additional insured.
- Verify workers' compensation is in force for all workers onsite.
- Read and sign a specific work authorization—never a blank or “open” contract.
- Request a summary of daily rates for extraction/drying equipment.
- Ask whether permits will be required for any demolition or rebuild.
- Take before-and-after photos even if the crew is documenting for you.
- Never pay front-to-back up front; deposits over one-third are a flag.
Be alert for tactics like dropping off a crew before you sign, pushing you to okay a blank work order, or stalling on providing documentation “until the insurance adjuster calls.” Reputable Springfield firms do not hesitate to provide paperwork up front, even when the clock is ticking.
Frequently asked questions — water damage restoration in Springfield
What does mold remediation cost in Springfield?
Mold remediation in Springfield typically costs between $1,700–$12,000, with the local average around $6,800. The wide range depends on how much area is affected, whether the growth is behind finished drywall, and whether clearance testing is required for insurance or sale. Since most Springfield homes were built before 1980, it's common for mold issues to be concealed in basements or behind kitchen and bathroom walls where leaks went unnoticed. Homes with extensive finished basements or where ductwork needs cleaning will be on the higher end of the range. Always ask if your contractor is following IICRC S520 standards and insist on clear boundaries of containment. Beware any firm that skips containment or offers “quick fogging” in this market—insurers won’t accept it, and neither will most real estate buyers.
Is basement flooding covered by insurance in Pennsylvania?
Homeowners insurance in Pennsylvania, including Springfield, will not cover water that enters your basement from the Schuylkill River or Wissahickon Creek—flood coverage is a separate policy with a defined waiting period. Typical policies pay for sudden and accidental plumbing failures but exclude “flood” as defined by FEMA: overland water or sewer backup without an endorsement. For example, if a supply line bursts and damages your finished basement, restoration and contents are likely covered up to your policy limits. If the creek rises and enters through your foundation, you’re only protected if you already bought flood insurance. With a full basement common here, the cleanup cost can easily reach $1,350–$8,500 after a clean-water loss.
Why does plaster take longer to dry than drywall?
In Springfield homes, especially those built before 1960, older interior walls may be plaster over wood lath, not drywall. Plaster is denser and retains moisture much longer, so after a water loss, structural drying can take a week or more (as opposed to 3–5 days for drywall). The initial extraction cost may be similar ($1,150–$8,000 for structural drying), but the dry-out phase will involve more equipment running longer. Plaster walls can also trap water inside wall cavities, particularly when behind vapor barriers or multiple coats of paint. Demolition is riskier, and the cost of returning plaster to pre-loss condition is almost always higher than with modern drywall construction.
How long before mold starts growing?
Under Springfield’s summer humidity, mold can begin to colonize damp drywall or wood in as little as 24 to 48 hours. Older homes with poor ventilation or hidden moisture behind finished basement walls are especially at risk. That’s why restoration contractors recommend beginning drying work immediately—delays of even a day or two raise risk and cost. If your home sits for more than three days after a water loss, expect at minimum to need limited mold remediation, not just drying. Mold remediation adds $1,700–$12,000 to a claim, so prompt extraction and dehumidification are the best investment you can make after a loss.
What is IICRC certification and does it matter?
IICRC stands for the Institute of Inspection, Cleaning and Restoration Certification. In Pennsylvania—and especially in Springfield, where there’s no state licensing for restoration—insurance adjusters expect to see IICRC-certified lead technicians for any claim work. The S500 (water) and S520 (mold) standards are the checklists that trained crews follow, and they mark the difference between drying that passes a moisture test and a job that ends up back on your policy a year later. Ask the lead technician for their IICRC card before agreeing to the scope. Even though anyone can print a business card in this state, only trained techs can answer your questions about legitimate costs, like the typical $4,400 for water extraction in Springfield.
What causes most water damage in Springfield homes?
Most water damage claims in Springfield come from aging copper supply lines behind drywall, water heater or washing machine failures, and sump pump problems in full basements. The post‑1945 tract construction boom brought copper plumbing into nearly every house, and at this age, small pinhole leaks or burst lines are all too common—often going unnoticed until drywall bulges or flooring starts to buckle. Raised basements and a region prone to freeze-thaw cycles add to the risk. Even minor “hidden” leaks can require a full-service extraction and structural drying, which typically cost $1,350–$8,500.
Does homeowner's insurance cover water damage in Springfield?
Standard homeowner’s insurance in Springfield covers sudden and accidental events like burst water supply lines, broken appliances, or ice dam leaks. What isn’t covered is water entering from the ground, flooding from the Schuylkill River or Wissahickon Creek, or gradual “maintenance” issues like slow leaks. For covered losses, your policy pays for both mitigation (emergency drying, extraction at $1,350–$8,500) and, usually, repair of finished walls and floors. Never let a contractor offer to “waive your deductible”—it’s prohibited by Pennsylvania’s Home Improvement Consumer Protection Act. Always review your insurance declaration page before signing any restoration contract.
Is bleach effective against mold?
In Springfield, many homeowners try bleach for mold cleanup, but it’s not effective on porous surfaces like drywall or wood framing. Bleach does not penetrate deeply enough to kill roots (hyphae), and in fact, using it on drywall can encourage regrowth by adding moisture. Proper mold remediation—priced between $1,700–$12,000—involves physical removal, HEPA vacuuming, and containing spores. Insurers and real estate inspectors expect documented remediation following IICRC S520, not a “bleach and paint over it” approach. Save bleach for hard, non-porous surfaces (like tiles), not for anything structural or in finished basement spaces.
Can I turn the dehumidifiers off at night?
No—turning off dehumidifiers or air movers even for a few hours undermines the entire drying plan. In Springfield’s humid climate, the risk of mold and secondary water damage rises fast if you stop the process. Most drying jobs here target a 3–5-day window, and your typical extraction/drying bill ($1,150–$8,500) assumes continuous operation. If equipment is too noisy or hot at night, ask your contractor to help relocate or adjust settings, but don’t unplug units—doing so could void mitigation guarantees or slow the process enough that contents or drywall must be removed.
How much does sewage backup cleanup cost in Springfield?
Cleanup after a sewage backup (“Category 3” water) in Springfield ranges from $2,800–$13,500, with most residential jobs landing between $5,000 and $8,000. This higher cost reflects the need for biohazard safety protocols, extra PPE, removal and disposal of all porous materials (finished drywall, carpets, upholstered furniture), and multiple rounds of sanitation and air cleaning. The Norristown Municipal Waste Authority’s wet-weather inflow issues have made these claims more common after storms. Most homeowner’s policies require a specific “sewer backup” endorsement, so always check your coverage limits before authorizing work.