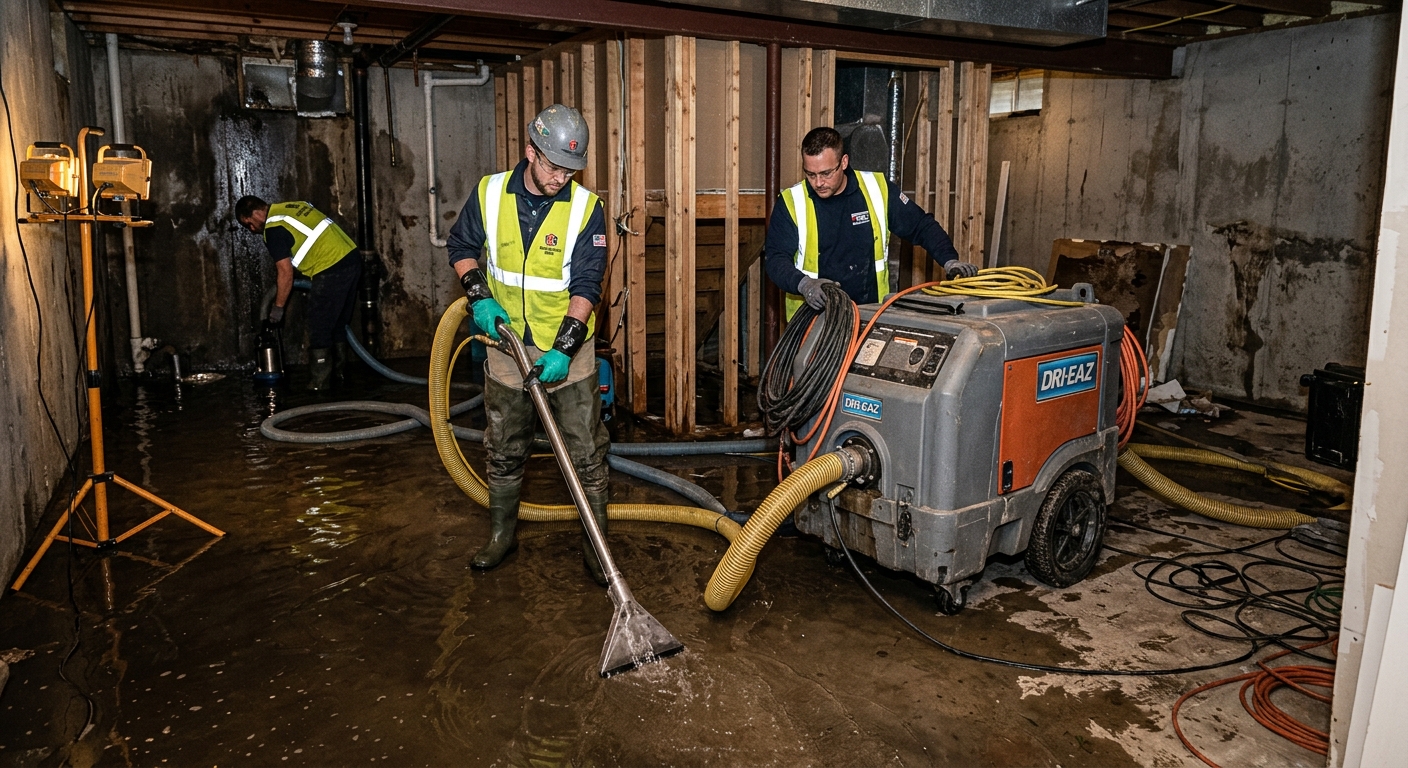
water damage restoration costs in West Earl — 2026
If you’re dealing with water pouring into your West Earl home right now, you want to know two things: how much this is going to cost, and how fast someone can stop the damage. In West Earl, prices for water mitigation and related services reflect the realities of local construction. With 78.9% of homes owner-occupied and 40.7% built before 1980 (U.S. Census Bureau, ACS 2024), water losses often mean dealing with aging plumbing, plaster walls, and finished basements. That, plus Lancaster’s history of frequent pipe failures in older rowhouses, pushes losses higher and makes multi-unit projects more complex than in newer suburbs.
It doesn’t matter if you have old cast iron drains, copper supply lines, or the latest PEX — when a main or appliance lets go, the first numbers you’ll see are for extraction and drying. Here’s what most homeowners are charged for common water restoration scenarios in West Earl:
| Service |
What it covers |
Typical duration |
Price range |
| Water extraction + emergency drying (Cat 1) |
extraction, air movers, LGR dehumidifiers, daily moisture monitoring |
3–5 days |
$1,250–$7,800 |
| Structural drying only (post-extraction) |
drying to standard after water is already out |
3–5 days |
$1,050–$7,300 |
| Mold remediation with containment |
containment, HEPA filtration, removal, antimicrobial, clearance test |
3–7 days |
$1,550–$11,000 |
| Sewage backup cleanup (Cat 3) |
biohazard protocol, disposal of porous materials, disinfection |
2–5 days |
$2,600–$12,500 |
| Emergency board-up / tarping |
stop further water entry, secure the structure |
same day |
$350–$900 |
Estimates for a typical West Earl home. Category, affected area and how long the water sat move these figures more than anything else.
What insurance covers — and the exclusion that surprises people
The costliest surprise for West Earl homeowners is that not all water damage is insured the same way. Damage from a sudden interior source — like a burst supply line in your basement — is typically covered under a standard homeowners policy, but surface flooding from heavy rain, Conestoga River overflow, or creek backup is excluded unless you specifically carry a separate flood policy. Many discover this only after a flood, finding themselves responsible for the bill.
There’s more to it: policies almost always exclude “maintenance” losses, meaning anything caused by slow leaks or neglect is on you. Sewer backup is also not included by default; you have to request a rider. In Lancaster County, where older sewer lines can back up into homes, this is one rider worth checking for.
Payout type matters, too: actual cash value only reimburses for the depreciated value of damaged materials, while replacement cost gets you the amount to put new for old — read your policy. The restoration contractor (or your insurer’s adjuster) will create a scope of loss: an itemized breakdown of what’s damaged and what mitigation/replacement will cost. This document is the basis for all negotiations and direct billing between the company and insurer.
Some firms offer “assignment of benefits,” where you sign rights to the claim over to the contractor. That may speed things up, but you lose control of payout negotiations. Pennsylvania’s Home Improvement Consumer Protection Act requires a written contract over $500 and gives you a three-day cancellation window. Be aware: waiving your deductible is prohibited in Pennsylvania — if anyone offers, they are asking you to commit insurance fraud. Choose companies who follow these rules and can show you their Home Improvement Contractor registration.
What construction era means for a water loss here
In West Earl, more than 40% of homes were built before 1980 (U.S. Census Bureau, ACS 2024), so a water loss here plays out differently than in a new Pennsylvania subdivision. If your house is older, you’re more likely to have copper or even galvanized plumbing and cast iron sewer lines, topped with thick plaster walls and hardwood floors over a full basement. When a pipe bursts, water moves fast through floor cavities and behind plaster, making extraction and drying harder — expect more wall demo and longer drying before reconstruction. Full basements collect more water and conceal trouble in insulation or behind paneling, which can mean hidden mold and extra remediation.
On the other hand, if your place is newer, say built after 1980, you likely have plastic (PVC or PEX) supply lines and drains, plus more drywall than plaster. Even if the materials are easier to dry and replace, most first-generation water heaters and supply pipes in these newer homes are reaching failure age, making sudden losses just as likely — just less complicated to put back together. West Earl’s typical home is not immune to water loss just because it’s newer. The era only decides how invasive the drying and tear-out will be.
Your belongings after a water loss
The structure is only half the claim after a water disaster; the rest is your belongings. Too many West Earl homeowners shortchange themselves on contents because they don’t document or inventory everything before the restoration crew starts moving and packing. For a thorough claim, photograph every room and item before anything leaves the premises. Restoration contractors will often perform a pack-out — carefully inventorying, boxing, and transporting salvageable belongings to an off-site cleaning facility.
Your insurance policy distinguishes between structure (walls, floors, built-ins) and contents (furniture, clothing, electronics, personal effects). After a Category 3 sewage loss, most upholstered furniture, mattresses, and particleboard shelving are unsalvageable and should be disposed of for health reasons. Solid wood furniture, electronics above water line, and area rugs with limited exposure are often worth cleaning and restoring. Insurers pay for cleaning only when it’s cost-effective compared to replacement, so you should discuss this line-by-line with both the contractor and your adjuster. Save all damaged items until your insurance company sees them, and push for a digital inventory to avoid gaps in your claim.
How long the whole thing takes
Most homeowners in West Earl expect the restoration job to run straight through, but in practice, this process breaks into two phases. The first phase — mitigation — is immediate and urgent: extraction, setting up air movers and dehumidifiers, and daily site checks until your home is dry. That portion usually wraps in under a week and may be direct-billed to your insurer, with invoices running from $1,250–$7,800 for extraction and drying or $2,600–$12,500 for Category 3 sewage cleanup.
The second phase is reconstruction — repairing damaged drywall, replacing flooring, repainting, and all finish work. This is scheduled after full drying and the insurer’s approval. In the Lancaster–Harrisburg market, competition is fierce and crews can mobilize fast for mitigation, but reconstruction slots often fill up quickly once a storm or freeze hits. Weeks or even months can pass between the drying equipment’s removal and a contractor being ready to rebuild. Homeowners often feel abandoned in this “quiet gap,” but it’s normal: the insurer must scope, approve, and issue payment before repairs begin. You aren’t forgotten — this is how the process works in nearly every West Earl loss.
The first hour: what to do before anyone arrives
If you find an active water leak in your West Earl home, here’s what to do — step by step:
- Shut off the main water supply. The main valve is usually in the basement or a utility area near where the service line enters.
- If the electrical panel is dry and safe to reach, shut off breakers feeding the flooded rooms. Don’t touch the panel if it’s wet or you’re standing in water.
- Take clear, timestamped photos and videos of the affected rooms and all personal property — before moving anything. Insurers rely on this evidence.
- Move smaller furniture, area rugs, and electronics off wet flooring to drier areas or up onto blocks. Prioritize things that can be easily dried or salvaged.
- Never use a household vacuum or shop vac to remove standing water unless it’s specifically rated for wet use and plugged into a dry, safe circuit.
After you’ve stopped the water and documented everything, call your insurance carrier right away. Whether you contact the restoration company first or the insurer matters less than making sure you’ve got photos and that there’s a claim number. The biggest mistake people in West Earl make is waiting until morning, thinking “it can dry out a bit.” Mold gets a running start in less than 24 hours, turning a
$4,100 water extraction into a
$6,200 mold remediation faster than you’d think. Act in the first hour — your wallet will thank you later.
Credentials and permits for restoration work in West Earl
Pennsylvania does not license restoration or mold contractors — there’s no state-issued restoration, water mitigation, or mold remediation license, and a business card doesn’t mean much here. The industry standard for quality is IICRC certification: ask to see the lead technician’s IICRC S500 (water damage) or S520 (mold) card. This is the expectation among insurers, even if it’s not written into law in West Earl.
You need a building permit if reconstruction follows a Category 2–3 water loss in Lancaster city, especially where structural repairs are needed. Minor drying jobs after small leaks (especially in county townships) are typically done without permits. Always ask up front if the contractor will pull permits — it’s their responsibility, not yours, when code enforcement is triggered.
Verify insurance and workers’ compensation coverage before anyone touches your house. Use the state’s WCIS system to check workers’ comp, and the PA Attorney General’s database for their Home Improvement Contractor registration. Prior to extraction, insist on a written contract — Pennsylvania law requires it for jobs over $500, and you get a three-business-day cancellation window for protection. If there’s any hesitation or lack of paperwork, move on — plenty of legitimate firms are available in the Lancaster–Harrisburg corridor.
Frequently asked questions — water damage restoration in West Earl
How long until reconstruction starts?
Reconstruction does not start immediately after mitigation in West Earl. Extraction and drying typically finish within 3–5 days, but then you’ll enter a waiting period while your insurer approves the scope of repairs and local contractors schedule you. With a saturated restoration market around Lancaster County, it’s not uncommon to wait anywhere from a few days to several weeks for reconstruction, especially during busy seasons when multiple pipe bursts or widespread flooding have overwhelmed crews. Your total timeline, from water loss to repairs finished, may stretch to four weeks or more if your claim involves a complex loss or mold remediation (which can run $1,550–$11,000). Ask your adjuster for updates, and get commitments in writing from your chosen contractor to avoid surprises.
How fast do restoration companies respond in West Earl?
Restoration companies in West Earl, part of the Lancaster–Harrisburg corridor, typically respond within 1–3 hours of your call — sometimes even faster for high-priority losses. The market here is crowded, with national brands like Servpro and ServiceMaster plus local outfits all operating crews nearby. This high competition usually means you won’t wait overnight during normal business hours or winter freeze events. Emergency board-ups or water extraction often begin the same day, with cost estimates starting at $1,250–$7,800 depending on severity and size. If you call after a widespread disaster, demand may push response times out, but you won’t see multi-day delays common in rural areas.
Is sewer backup covered under a standard policy?
In West Earl and throughout Lancaster County, sewer or septic backup is not covered under a standard homeowners policy by default. Many homeowners only discover this after a catastrophic backup, especially in parts of Lancaster city where aging combined sewer systems increase risk. To protect yourself, you need a specific sewer or sump backup rider, usually for a small additional premium. Restoration costs for a Category 3 backup (biohazard) typically fall between $2,600–$12,500. If you’re not sure your policy includes this endorsement, call your agent — it’s much cheaper to add now than to pay out-of-pocket later, especially given local conditions.
Does homeowner's insurance cover water damage in West Earl?
Most standard policies in West Earl cover “sudden and accidental” water damage, such as burst pipes or appliance failures inside the home. However, groundwater or surface flooding from the Conestoga River, neighborhood runoff, or rain is excluded unless you have a separate flood policy. Coverage can also get denied for neglected maintenance or slow leaks. Insurance will typically pay for emergency drying and water removal (from $1,250–$7,800), damaged building materials, and sometimes professional mold remediation if the loss is reported quickly. Always check your terms: sewer backup requires a rider, cosmetic repairs may not be covered, and all claims need prompt documentation and fast reporting to avoid disputes.
How much does a flooded basement cost to restore in West Earl?
The cost to restore a flooded basement in West Earl depends on how long the water sat, the source, and whether contaminated water (Category 2/3) is involved. For a clean water event caught early, plan for extraction and drying in the range of $1,250–$7,800. If water lingered for more than 24–48 hours, or if sewage or groundwater is present, costs jump significantly. Mold remediation or Category 3 cleanup pushes bills toward $2,600–$12,500. Finished basements, common in Lancaster County’s full-basement homes, cost more due to drywall, insulation, and additional contents. Always ask for an itemized estimate before work begins.
What is Category 3 black water?
Category 3 “black water” refers to water damage involving severe contamination — typically sewage backup, floodwater from rivers, or water that’s been standing long enough to support substantial microbial growth. In West Earl, this often means water coming in from the Conestoga River, a sewer line failure, or a major plumbing backup, especially in older homes with aging drains. Cleanup for Category 3 is more expensive (usually $2,600–$12,500) because all porous materials (like carpet, drywall, and upholstered furniture) have to be removed and disposed of safely, and extensive disinfecting is required. Don’t attempt to DIY this: the health hazards are real and insurance will expect certified contractors.
Can I rent dehumidifiers instead of hiring a company?
It’s possible to rent dehumidifiers from a hardware store in West Earl, and you might consider this for a pinhole leak on a concrete floor, but rental units simply can’t match the drying capacity of a professional LGR (low grain refrigerant) dehumidifier or air movers used by restoration companies. These companies set up equipment and monitor moisture at multiple points, a process reflected in the structural drying only cost of $1,050–$7,300. Rental may save a few hundred dollars for very minor events, but if water has migrated under flooring, into cavities, or sat for more than a few hours, DIY drying increases the risk of hidden mold or rot — often costing more to fix in the end. When in doubt, get a professional moisture assessment up front.
Is sewer backup a known problem in West Earl?
While West Earl isn't part of Lancaster city, the entire region, including West Earl, takes its cue from the city’s known issues with localized sewer backup due to aging sewer segments. West Earl has homes with full basements and older connections — both factors increasing risk, especially during heavy rain or freeze-thaw cycles that impact sewer flow. The cost to remediate a sewer backup here falls in the $2,600–$12,500 range, depending on the contaminated area. Anyone with a finished basement in West Earl should review their insurance and consider a sewer backup rider to cover these not-uncommon events.
What does structural drying cost if I extracted the water myself?
If you managed to extract most of the standing water on your own, you may only need professional structural drying. In West Earl, this service typically runs between $1,050–$7,300, depending on home size and how far water migrated behind walls, into subfloor, and insulation. This still covers industrial dehumidifiers, air movers, and daily moisture monitoring by a certified crew. In older homes with plaster or thick wooden elements, costs trend higher due to longer dry-out times. Always ask for a detailed drying plan and post-service moisture readings to be sure the job is finished safely.
Does Pennsylvania license mold remediation contractors?
No, Pennsylvania does not have a state-issued license for mold remediation contractors. In West Earl and all of Lancaster County, anyone can legally offer mold cleanup. However, insurers and most professionals expect crews to follow IICRC S520 standards and show up with third-party certification. The going rate for certified mold remediation with containment is $1,550–$11,000 in West Earl. If you’re hiring someone, ask to see their IICRC credentials and check references. Make sure the contract specifies containment, post-remediation clearance testing, and exactly what areas will be opened and restored.