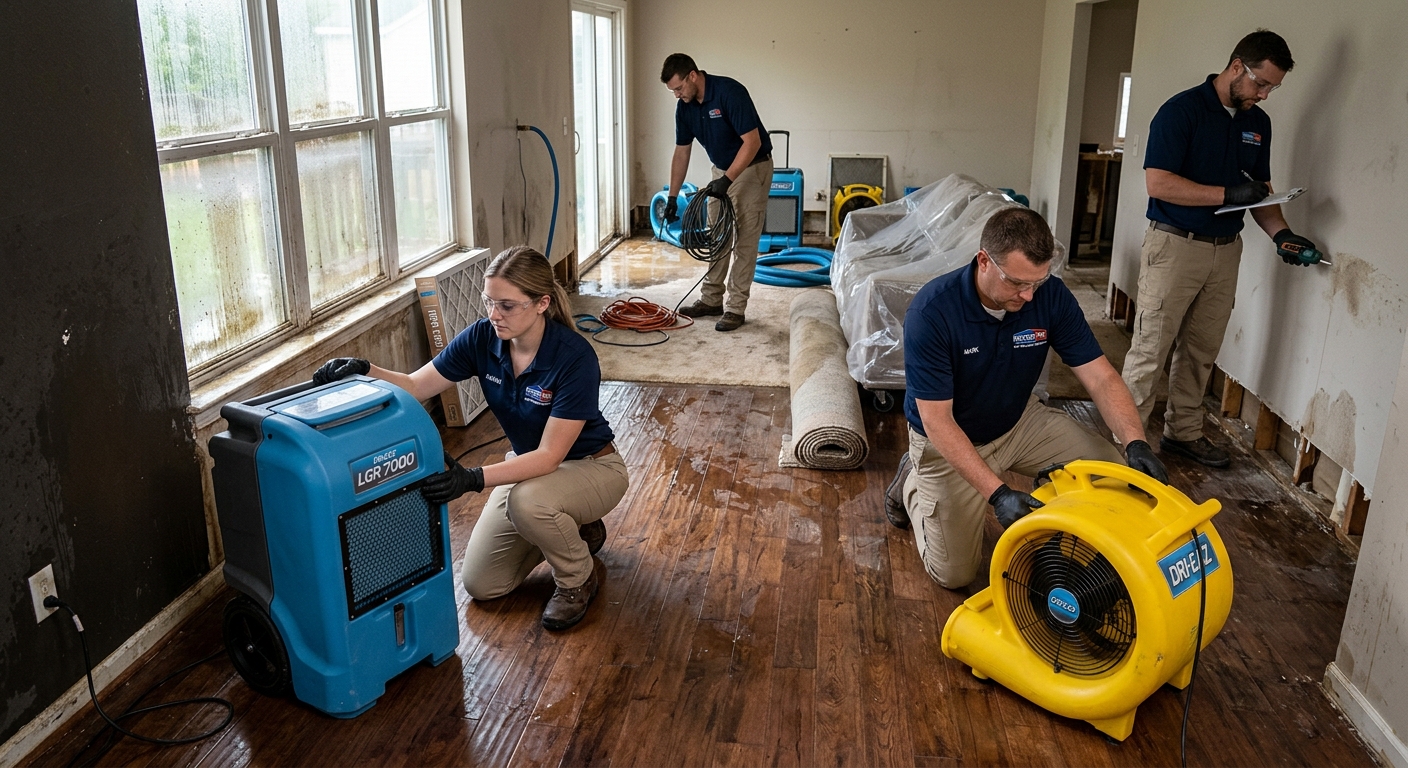
Palmer water damage pricing by scope — 2026
If you’re dealing with water everywhere in your Palmer home right now, you need hard numbers. Costs here are shaped by Palmer’s housing profile: with 49.1% of homes built before 1980 and nearly 68% single-family, many contain older plumbing and full basements—exactly where pipe failures and seepage often start, especially in the dense 1900–1940 stock found in nearby Bethlehem and Easton. This leads to more frequent plaster repair needs and basement water extractions compared to newer construction towns.
Here’s what you can expect to pay in Palmer for the most common types of residential water damage response:
| Service |
What it covers |
Typical duration |
Price range |
| Water extraction + emergency drying (Cat 1) |
extraction, air movers, LGR dehumidifiers, daily moisture monitoring |
3–5 days |
$1,300–$8,200 |
| Structural drying only (post-extraction) |
drying to standard after water is already out |
3–5 days |
$1,100–$7,600 |
| Mold remediation with containment |
containment, HEPA filtration, removal, antimicrobial, clearance test |
3–7 days |
$1,650–$11,500 |
| Sewage backup cleanup (Cat 3) |
biohazard protocol, disposal of porous materials, disinfection |
2–5 days |
$2,700–$13,000 |
| Emergency board-up / tarping |
stop further water entry, secure the structure |
same day |
$350–$900 |
Estimates for a typical Palmer home. Category, affected area and how long the water sat move these figures more than anything else.
Preventing the next one
In Palmer, prevention is about picking the most cost-effective upgrades for your home’s age and construction, not buying every gadget. If you only do one thing, replace old washer and water heater supply lines—often for under $75–$150 per appliance, including robust braided lines—since these fail frequently in homes built before 1980. Next, sump pumps with battery backup: this costs $450–$1,100 installed, but makes all the difference in older Palmer basements prone to seepage and Lehigh River overflows.
Automatic water shutoff valves can stop major flood losses and cost about $250–$800 installed, but you don’t need these unless you travel often or have a history of major leaks. A backflow valve: worthwhile if you live in Easton’s older neighborhoods where sanitary sewer backups happen, with typical installation running $900–$2,300. Leak sensors offer peace of mind for $25–$75 per unit—just place them under water heaters and near pumps, and skip the fancy systems unless you love smart-home tech.
In our climate—expecting 4 °F winter nights and a 36-inch frost depth—insulate vulnerable pipes and shut off outside spigots before winter. Water heater pans and drains are only worth the trouble if your heater sits over finished space; in unfinished Palmer basements, let gravity do its work.
What to expect week by week in Palmer
Water damage recovery in Palmer can feel like a sprint followed by a confusing pause. The initial phase—mitigation—begins within hours: crews remove water, set up air movers and dehumidifiers, monitor daily, and usually finish after 3–5 days. This is direct-billed, urgent, insurance-driven, and handled by IICRC-trained techs who bring all the gear.
The gap comes next. Once the equipment is gone and moisture readings are normal, there’s a lull before reconstruction starts. In Palmer, with multiple regional firms but lots of older housing, lead times for drywall, plaster, or flooring repairs usually stretch to 2–4 weeks—and that’s on the short side when everyone’s pipes burst in January.
Reconstruction—replacing what was removed—runs by permit and is often a new contract with different subs. It’s not unusual for homeowners to feel lost during the wait. This is where staying in touch with your adjuster and contractor pays off. Don’t hesitate to ask for updates; you’re not being difficult. Most delays reflect skilled labor supply across the Lehigh Valley, not anyone ignoring your job.
Palmer's flood exposure and what it means for coverage
Palmer’s geography, near both the Lehigh River and Delaware River corridors, means certain homes face real overbank and storm-flood risk. If you live close to these waterways or in a mapped floodplain, standard homeowners insurance in Palmer will not cover flood damage—even though burst pipes and flooding often look identical when the water’s ankle-deep by morning.
Flood insurance is always a separate purchase, typically underwritten through the National Flood Insurance Program (NFIP), and it’s only available if bought in advance—there is usually a 30-day waiting period. Flood zone maps are public, so you can check your own risk, but be aware that even non-designated lots have seen water in extreme events.
The crucial detail: insurers treat a burst pipe and river water very differently. Pipe bursts or failed sump pumps (if the source is inside) usually fall under your main policy. Muddy water entering from outside, even if it broke through a window, counts as flood—no coverage unless you carry the flood rider or special policy. The adjuster will ask questions about the source and direction of travel, not just what’s wet.
What proper drying actually looks like
In Palmer, you should expect more than just fans: proper drying relies on measured, recorded, and repeatable steps, driven by IICRC S500 standards. After extracting water, crews map all wet areas with moisture meters—especially vital in older homes with plaster walls or multiple hidden cavities common in Bethlehem and Easton stock. They’ll establish a drying goal, based on manufacturer data or unaffected material readings, not a wild guess.
Your crew should set up air movers to force dry air across every wet surface and use LGR (low grain refrigerant) dehumidifiers to pull moisture out of the air, vital in our climate with its 6,100 heating degree days (lots of cold, low-ventilation months). All equipment must stay running day and night; shutting things off overnight can actually set you back an entire day’s progress.
Expect daily monitoring visits where the tech checks temperature, humidity, and takes fresh meter readings—recorded in a daily log. This is non-negotiable: if you ask to see the logs and they cannot produce them, something is wrong. When readings hit the drying goal, only then do they pull out equipment, not before. Anything less is just theater.
What a Pennsylvania restoration contractor must actually hold
Pennsylvania does not license water damage or mold remediation contractors—no matter what a business card might claim. Instead, the de facto expectation is IICRC S500 certification for water damage (and S520 for mold), which is what insurers and adjusters look for in Palmer and the rest of Northampton County. Always ask to see the lead technician's current IICRC card before work begins; it’s your main assurance of training.
No building permit is required in Palmer for emergency extraction and drying with portable equipment, but if you move to reconstruction—especially replacing drywall in Bethlehem—it’s a permit job and must go through the local code office. For contracts over $500, restoration contractors must hold a Home Improvement Contractor (HIC) registration. Confirm this registration yourself online before signing.
Don’t just take a certificate: always ask for a certificate of insurance showing active liability and workers’ compensation, which you can look up in the WCAIS system. Before you let anyone pump a basement or pull up floors, have in writing: the HIC registration number, scope of work, and pricing terms.
Who pays for water damage in Palmer
The number-one cost difference for Palmer homeowners: water that starts from inside (like a burst supply line) is usually covered by standard insurance, while water coming in from the Lehigh or Delaware River—or any floodplain—is not and requires a separate flood policy. Many in Palmer learn this only after the fact, when their insurer denies an overbank claim that looks exactly like a pipe burst on the surface.
Homeowners policies also exclude slow, long-standing leaks or preventable maintenance issues—so that small drip behind the wall that went undetected for months is often on you. Easton’s periodic sanitary sewer backups are typically not covered unless you’ve added a sewer backup rider, a small extra premium, but essential in the older local housing stock. Expect limits on sewer backup coverage, sometimes capped below the actual restoration costs, which run $2,700–$13,000 here.
Claims for sudden water losses are adjusted by “actual cash value” (depreciated amount) or “replacement cost” (what it takes to restore, minus deductible). Understand which you have, as the difference can be many thousands. The scope of loss document your contractor provides is the blueprint for your adjuster’s payment—get a copy and review it before approving any repairs beyond mitigation.
Direct billing (“assignment of benefits”) means you sign over insurance proceeds to your contractor. The pro: you don’t have to pay up front or chase reimbursement. The con: you lose some control over the process and must trust your contractor’s billing aligns with the insurer’s limits.
The Home Improvement Consumer Protection Act requires a written contract over $500, and you always have a three business-day right to cancel. Waiving your deductible is illegal here—an offer to do so is a red flag for insurance fraud. If a company suggests it, look elsewhere.
Frequently asked questions — water damage restoration in Palmer
Is emergency after-hours service more expensive in Palmer?
Emergency after-hours water extraction in Palmer, like anywhere in the Lehigh Valley, typically costs more than work done during regular business hours. Many firms serving Northampton County, including Palmer, operate 24/7 because pipe breaks and sump pump failures in the region's older homes don't respect the clock. For a basic water extraction plus drying callout at 2 a.m., the service fee may be higher, but most reputable firms include after-hours rates in their standard price range of $1,300–$8,200 if it's a Category 1 (clean water) loss. Do ask about any additional emergency charges before you authorize work, but beware those quoting way outside this band—they're either price-gouging or skipping steps.
Does wet insulation have to be replaced?
In Pennsylvania—including Palmer—wet insulation almost always has to be replaced, especially if fiberglass batts are saturated or if the water comes from a contaminated source (like a Category 3 sewage backup). Insulation in the region’s older homes, often packed in basement rim joists or exterior walls, loses its thermal value when soaked and can support mold growth within days given our local climate. A standard water extraction plus structural drying job runs from $1,100–$7,600, but re-insulating walls or attic spaces is typically billed as a separate reconstruction expense. Don’t let a restoration crew tell you they can “just dry it in place”—that’s not sound practice for Palmer’s housing stock.
Do I need separate flood insurance in Palmer?
Yes, separate flood insurance is necessary in Palmer if you want protection from overbank floods due to the Lehigh River or Delaware River. Standard homeowners insurance won’t touch water that enters from outside at ground level, no matter how similar the cleanup may look. Coverage is purchased as a distinct policy, often through the NFIP, and pricing depends on your specific flood zone and structure. Typical water extraction and drying after a covered flood would still cost between $1,300–$8,200, but you’ll pay out of pocket if you lack the correct policy. Remember: flood insurance takes at least 30 days to go into effect, so waiting until a rainstorm is forecasted won’t help.
Can I turn the dehumidifiers off at night?
No—you should leave dehumidifiers and air movers running 24/7 until your restoration crew says the job is complete. In Palmer’s climate (with 6,100 heating degree days), cutting power at night slows the drying process and risks mold growth, especially in older homes with horsehair plaster or unfinished basements. Typical costs for water extraction and structural drying—$1,100–$7,600—reflect the need for continuous drying, not just daytime activity. If a crew says it’s fine to switch off equipment to save energy, press for a written drying plan and moisture logs. The difference between two and five days of drying often traces back to how consistently the equipment ran.
How much does sewage backup cleanup cost in Palmer?
Sewage backup in Palmer is more common than you’d expect, given the older sanitary systems in Easton and nearby areas. Cleanup isn’t just dirty—it’s a full biohazard protocol, requiring trained workers, disposal of all porous materials (think carpets, drywall up to several feet), and multiple rounds of disinfection. The price for professional sewage (Category 3) cleanup here runs from $2,700–$13,000, depending on how far the water traveled and what got contaminated. Add another few thousand if you need entire rooms re-floored or walls rebuilt. Homeowners insurance rarely covers this unless you have a sewer backup endorsement—so check your policy before you need it.
Do older Palmer homes need different treatment?
Absolutely. Palmer and its neighboring towns have thousands of homes built before 1940, many with plaster walls, full masonry basements, and complex hidden cavities. Restoration in these houses often costs more—water can run behind plaster and lath for days, and old-growth wood responds differently to moisture than modern framing. Structural drying or mold remediation typically lands in the region of $1,650–$11,500, depending on complexity. Be sure your contractor is experienced with historic materials, not just drywall, and demands drying logs for every surface. Rushing the process or using someone inexperienced can cause long-term damage in these homes.
Does Pennsylvania license mold remediation contractors?
No—there is no state licensing statute for mold remediation contractors in Pennsylvania, including Palmer. The standard that matters in this market is IICRC S520, which responsible firms follow for containment, HEPA filtration, and clearance testing. Expect mold remediation jobs to run from $1,650–$11,500 depending on extent. Always ask for proof that your restoration crew leader is IICRC certified and get references from actual customers in Northampton County. Be wary of any company suggesting a Pennsylvania license for mold removal—they’re likely confusing you on purpose or don’t know the rules themselves.
Is basement flooding covered by insurance in Pennsylvania?
In Palmer and across Pennsylvania, insurance coverage for basement flooding depends on the water source. If your finished basement gets wet from a burst pipe or broken washing machine supply line, you’re usually covered under your regular homeowners insurance. But if the water comes through the foundation or is the result of Lehigh River or Delaware River overflow, that’s only covered with a dedicated flood policy. Clean water extractions run $1,300–$8,200 in Palmer—if you have coverage. Sewer backup? Only if you purchased that specific rider, especially important in older homes. Always ask your agent to clarify exclusions, and review your coverage annually against your home’s risk profile.
Can I rent dehumidifiers instead of hiring a company?
You can rent dehumidifiers in Palmer, but understand the limits. Typical home improvement stores will rent small consumer-grade machines for $50–$120 per day, but these are not LGR units and cannot keep up with significant water loss—especially not in big spaces or during winter with closed windows. Professional restoration companies use industrial equipment capable of meeting industry drying standards, plus documentation your insurer will expect if you file a claim. Also, unaddressed hidden moisture behind walls or under flooring can lead to future mold, and insurance won’t cover subsequent damage if you DIY but don’t achieve proper dry-out.
How fast do restoration companies respond in Palmer?
Palmer benefits from a dense restoration market, with multiple regional firms operating out of Bethlehem and Easton. In most cases, you can expect a response within a few hours for true emergencies. For standard clean water extractions, same-day service is the norm—at a median price around $4,300. During major weather events, response times may stretch a bit as demand spikes, but Palmer typically sees faster service than more rural areas of Northampton County. Always confirm availability before authorizing any mitigation work, and verify that the crew is IICRC certified and HIC registered to avoid problems down the line.