What water damage restoration costs in Somerset
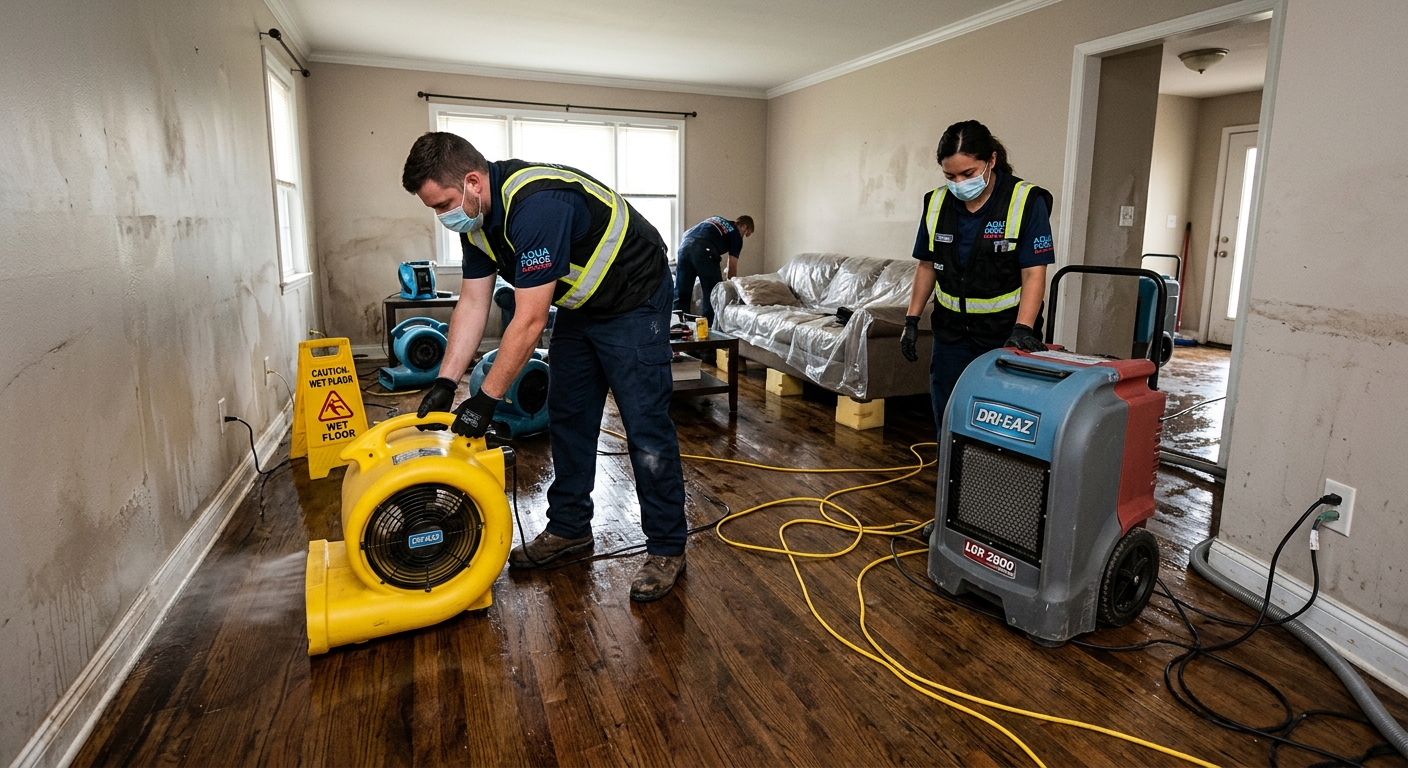
Somerset homes face water damage costs shaped by both age and local construction — if you’re reading this during an emergency, you’re not alone. Most houses here were built between 1900 and 1940, meaning antiquated plumbing and unlined masonry basements are the norm. Those two facts drive frequent and sometimes complicated water losses, especially during freeze-thaw spells. Nearly 64% of homes are over 40 years old (U.S. Census Bureau, ACS 2024), so water finds weaknesses fast. Pricing here isn’t just about square footage: structural layout, how long it sits, and source all move the number, and travel surcharges aren’t rare in Somerset County’s thin rural market. Costs bump up further when the Stonycreek River or Quemahoning Creek pushes over. Whether you just discovered a puddle from a broken line or a couple inches from a backup, here is what the main services actually run in this county — figures shown are for a typical single-family house, following supply line failures or backups in an unlined basement like so many in the borough:
| Service | What it covers | Typical duration | Price range |
|---|
| Water extraction + emergency drying (Cat 1) | extraction, air movers, LGR dehumidifiers, daily moisture monitoring | 3–5 days | $1,100–$6,900 |
| Structural drying only (post-extraction) | drying to standard after water is already out | 3–5 days | $900–$6,500 |
| Mold remediation with containment | containment, HEPA filtration, removal, antimicrobial, clearance test | 3–7 days | $1,400–$9,700 |
| Sewage backup cleanup (Cat 3) | biohazard protocol, disposal of porous materials, disinfection | 2–5 days | $2,300–$11,000 |
| Emergency board-up / tarping | stop further water entry, secure the structure | same day | $350–$900 |
Estimates for a typical Somerset home. Category, affected area and how long the water sat move these figures more than anything else.
Choosing a restoration company in twenty minutes
Somerset County’s market isn’t crowded — there are just a handful of local outfits and some regional franchises serving the county with rotating crews. The honest truth is that in rural southwestern Pennsylvania, the first company able to send someone isn’t always the right call. ServiceMaster, SERVPRO and a few others cover Somerset, but travel surcharges apply because the closest hubs are in Johnstown or Pittsburgh. Still, you can vet intelligently on a tight clock.
Before letting anyone show up, confirm these three things on the phone: whether the company has active Home Improvement Contractor (HIC) registration (PA law requires this for jobs over $500), that they carry current workers’ compensation coverage for their techs, and that they’ll send an IICRC-certified lead (these are the actual industry and insurer standards here). Somerset does not regulate restoration or mold with state licenses—so a plastic badge doesn’t prove qualification—but don’t skip these documents.
- Company’s HIC registration number (verify at hic.attorneygeneral.gov)
- Proof of workers’ compensation (ask for WCAIS verification)
- IICRC certificate, showing S500 or S520 training for water damage or mold
- Certificate of insurance (name you as certificate holder)
- Written work authorization or contract (required by law over $500)
- Clear scope of work—avoid open-ended “restoration services as needed” lines
- Detail on whether equipment rental/travel will be surcharged in Somerset
- Who handles permit application, if structural work is needed
- Written daily moisture logs (should be routine for reputable firms)
- What clearance measures (air/mold testing) are used for completion
Watch out for pressure: some crews will push to start unloading before you’ve agreed to anything (“just sign here to let us get going”), or provide a blank-scope contract that authorizes all services up to an unstated cap. Always insist on getting their HIC number and checking insurance before they touch anything; it’s your legal right, and it’s never “just paperwork.”
What to expect week by week in Somerset
Water restoration in Somerset divides into two phases that are often confused: mitigation and reconstruction. The first is emergency—rapid water extraction, drying, and containment to prevent further damage and mold. For most Somerset homes, this is a matter of three to seven days, depending on contamination and severity. Local contractors generally direct-bill insurers for this phase, and you’ll see daily visits to monitor drying and swap equipment.
Once the last air mover leaves, however, is when most homeowners feel the process grinds to a halt. If repair or rebuild is needed—such as new drywall, flooring, or structural work—this triggers the reconstruction phase. Here’s where lead times in Somerset are longer than Pittsburgh or Johnstown: crews are thin, permits for any work affecting structure in Somerset Borough require code office approval, and reconstruction is nearly always a separate contract. It can take anywhere from two weeks to several months to start and finish, especially if specialized trades are needed or materials have to be ordered.
The period between phases, when your house is dry but not put back together, is the most frustrating. Expect a gap—often one to four weeks—while scopes are written, insurance figures are hashed out, and crews are scheduled. Knowing this ahead means you can plan for alternate living arrangements or minimize surprises as you wait.
Who pays for water damage in Somerset
The single most expensive difference for Somerset homeowners is this: your standard policy covers sudden, internal water releases—like a burst washer supply line—but excludes surface flooding from outside the house. If water comes up from the Stonycreek or flows through the basement windows, that counts as a flood, and you’d need a separate flood insurance policy for coverage. This catches many Somerset Borough residents off guard, especially with the older unlined basements in the area.
Insurance will often deny claims for gradual leaks, seepage, or deferred maintenance—such as a slow-dripping pipe behind 1930s plaster. Sewer backup, which is a real risk in Somerset’s downtown laterals during storms, is frequently excluded unless you add a sewer or sump backup rider. Most policies pay at “actual cash value” (depreciated) unless you’ve chosen “replacement cost” coverage, which can mean thousands less on a claim for old finishes. Your contractor should prepare a scope of loss document—a detailed breakdown of what was damaged, what’s required to fix it, and what’s excluded. This is what your insurer uses to settle up.
Direct billing and assignments of benefits (AOB) are common in the trade. Direct billing means the contractor seeks payment directly from your insurer, sometimes reducing your paperwork headache. With AOB, you sign over claim rights to the contractor—they negotiate and settle with the insurer. This can speed things up, but read closely: you may lose control if costs balloon.
Under the Pennsylvania Home Improvement Consumer Protection Act (HICPA), your contract must be in writing if work exceeds $500, and you get a three-day right to cancel. Waiving or absorbing your insurance deductible is not allowed here—a company offering to “cover your deductible” is breaking the law and probably cutting corners elsewhere. That’s a red flag worth walking away from.
Credentials and permits for restoration work in Somerset
Restoration and mold work in Somerset is not subject to any state trade licensing—Pennsylvania does not license water mitigation or mold remediation contractors, and no special certificate is needed from the commonwealth. Homeowners should not assume that advertising or a business card means the crew has formal restoration training. The actual industry and insurance standard is IICRC certification—specifically, S500 for water loss and S520 for mold.
Before the first fan is set, ask to see the lead technician’s IICRC card if mold or water damage work is promised. Locally, only reconstruction or demolition that affects structure or building systems (such as electrical or drywall replacement) after water loss typically requires a permit in Somerset Borough; emergency extraction and drying does not require one in most of the county’s townships.
Every job over $500 requires HIC (Home Improvement Contractor) registration. Verify this online before anyone starts (hic.attorneygeneral.gov). Always request written proof of workers’ compensation—this protects you if a tech is injured on your property. Use WCAIS (wcais.pa.gov) to check coverage.
Have the company issue a written work scope that lists services and rates, signed by both parties, before a single piece of equipment is unloaded. For any job in a pre-1978 house, if disturbance is expected, you may also request documentation of EPA Lead RRP certification for disturbance of painted surfaces.
Why your neighbour's bill was half of yours
Homeowners in Somerset often compare water loss bills and wonder why the same-sounding job can run twice as much next door. The reason lies in two separate factors: category (how contaminated the water is) and class (how much the structure and materials have absorbed). It’s easy to conflate the two, but they operate independently—and the highest bills are not always for the biggest floods.
Category refers to water quality, running from clean (Category 1) to black water (Category 3). A small toilet backup (Category 3) in a basement can actually cost more than a major clean-water leak, because Category 3 requires full biohazard protocol and disposal of porous items—think $2,300–$11,000 even for contained areas. Class, on the other hand, describes how ‘deep’ the water has gone: if only the surface is wet and nothing soaks in, you can land at the low end of the spectrum ($1,100–$6,900).
The most overlooked fact: water changes category as it sits. A supply line burst is Category 1 for hours but can become Category 2 or even 3 if left a couple days—especially in Somerset’s clay-and-shale subgrade basements. That means acting quickly isn’t just about speed; it’s about preventing a clean-water event from ballooning into a full remediation job.
| Classification | Source or extent | Health risk | Cost effect |
|---|
| Category 1 — clean | supply line, appliance line, rainwater | low | baseline |
| Category 2 — grey | washing machine, dishwasher, sump failure | moderate | +20–40% |
| Category 3 — black | sewage, groundwater, water standing 72+ hrs | biohazard | $2,300–$11,000 |
| Class 1 | small area, little absorption into structure | — | low end of $1,100–$6,900 |
| Class 2 | whole room, water into walls and subfloor | — | $1,100–$6,900 |
| Class 3 | saturation from above; insulation and walls wet | — | $900–$6,500 |
| Class 4 | deep saturation of hardwood, plaster, concrete | — | service2 upper range |
Flooding vs plumbing failure in Somerset
Not all water losses look the same to your insurer, even if cleanup is identical to the naked eye. In Somerset County, addresses near the Stonycreek River or Quemahoning Creek face a real risk of flooding that standard policies don’t touch—coverage for this must be purchased separately, often through the National Flood Insurance Program. That separate coverage carries a waiting period (typically 30 days), so it can’t be rushed when heavy rain is in the forecast or rivers start to rise.
If you’re in a FEMA-designated flood zone, your lender will likely require flood insurance—but even out of the mapped zone, groundwater and overbank water are still excluded from most standard homeowner’s policies in Somerset. Conversely, if the loss comes from a burst supply line or a broken appliance inside, that usually falls under “sudden and accidental” perils.
One of the toughest moments for Somerset owners is having an adjuster declare their loss as “flood” (uncovered), not internal “leak” (covered), despite damage that looks the same—wet drywall, ruined carpet, standing water in the basement. Immediate documentation and clarity on water source are the only leverage you have for a favorable claim.
Frequently asked questions — water damage restoration in Somerset
What is Category 3 black water?
Category 3, or "black water," is water that's grossly contaminated – this means sewage, river water, or any water that's been standing for 72 hours or more. In Somerset, this often comes from sewer backups in downtown properties or floodwaters from local creeks. Category 3 cleanup isn’t just more expensive ($2,300–$11,000) – it also requires biohazard protocols: removing drywall, insulation, carpeting, and any porous contents it touches. The risk is genuine: exposure to pathogens, mold, and chemicals. That's why reputable Somerset restoration firms wear full PPE and separate contaminated materials for disposal. Don’t let anyone sell you “just a drying” if you’ve had a sewage backup or flood—the danger lingers unless you strip back to clean structure and fully sanitize.
How long until reconstruction starts?
After the emergency drying phase in Somerset, reconstruction rarely starts right away. Because local restoration crews are thin and building supply shops don’t have city hours, the wait between mitigation and repairs is often two to four weeks—sometimes longer during storm season. Permits for structural or system work in Somerset Borough and nearby townships can introduce further delays, as the local code office reviews every application. Use this downtime to make design decisions or select replacement materials. If you expect a full rebuild, budgeting for the higher end of service ($6,900+) isn’t uncommon, and it’s realistic in a 1930s basement with deep water intrusion.
Can I rent dehumidifiers instead of hiring a company?
You can, but Somerset’s climate and home stock make this risky for anything beyond the smallest spills. Big-box stores will rent you consumer-grade dehumidifiers and fans, but they lack the drying power (and moisture tracking) of commercial LGR equipment that restoration companies bring. If you have a couple gallons on a slab floor, DIY might work—otherwise, you could end up saving a few dollars up front but losing thousands on mold or hidden structural damage later. Professional emergency drying in Somerset typically runs $1,100–$6,900, but it comes with daily moisture readings, the right drying plan, and—importantly—documentation your insurer will actually accept for full reimbursement.
Should I call my insurer or a restoration company first?
If you’re staring at inches of water, call a reputable Somerset restoration company first—they can usually arrive faster and start limiting damage right away. Notify your insurer as soon as possible (take photos and video), but don’t wait for adjuster approval to get drying started or you risk your clean-water loss becoming a Category 3 event. Emergency extraction and drying often falls in the $1,100–$6,900 range, and delays can more than double costs. Just be sure the company you choose follows legal requirements for contract and insurance disclosures for Pennsylvania.
How does southwestern Pennsylvania's climate affect drying times?
Somerset’s freeze-thaw cycles and humid summers both work against you. In spring and early summer, the air is often saturated, which can slow drying times and force crews to run more dehumidifiers—especially in old masonry basements common here. Winter drying isn’t much faster; cold air means less evaporation and harder work for the drying gear. Sometimes, a basic dry-out can stretch to $6,500 or more if your house has thick plaster, insulation, or brick. The short version: old houses here dry slower, not faster.
What does mold remediation cost in Somerset?
Mold remediation with containment, HEPA filtration, and post-clearance testing typically runs $1,400–$9,700 for a Somerset home. The wide range is because every job is different: some require only small-area cleaning and sealing, while others involve gutting half the basement and running negative-air machines for days. Given that much of Somerset County’s housing is from the 1900–1940 era, hidden cavities and repeated water losses in unlined basements make complete remediation on the higher end more common here than in new construction.
What is an assignment of benefits and should I sign one?
An assignment of benefits (AOB) is a legal document where you turn over your insurance claim rights to the restoration contractor—they deal directly with the insurer and get paid directly. In Somerset, this is an option for peace of mind, but it comes with trade-offs: you give up control over scope, cost, and repairs. If the company you choose is solid and prices in line with the local band ($1,100–$6,900 for water extraction), AOB can speed things up. But be wary: unscrupulous operators occasionally use AOB to inflate claims or start work you didn’t authorize. Read every contract completely before signing, and never rush if you feel pressured.
What is IICRC certification and does it matter?
IICRC stands for Institute of Inspection, Cleaning, and Restoration Certification. While Pennsylvania doesn’t license restoration or mold contractors, the IICRC S500 (for water) and S520 (for mold) are the standards insurers expect. Certified techs have been trained on drying methods, safety, and category/class distinction. Always ask for the IICRC card from the lead tech—this isn’t just a hoop to jump through: it means your Somerset loss will be handled with proper documentation and process. Mistakes by untrained crews can drive a small event ($1,400) up to a major one if they miss hidden moisture or cross-contaminate Category 3 areas.
Is emergency after-hours service more expensive in Somerset?
Yes, you should expect a surcharge for after-hours or weekend emergency calls—especially here, since crews travel in from Johnstown or Pittsburgh and run leaner operations. The typical Somerset range for an after-hours emergency water extraction is $1,100–$6,900, but you may see an extra $300–$600 on top, or a minimum fee. For small incidents, waiting until morning can save you, but for anything Category 2 or higher, the damage from delay can add more to your bill than the after-hours callout.
What if the insurer's estimate is lower than the contractor's?
It’s common in Somerset for local restoration contractors to provide a scope that exceeds your insurer’s first offer—especially in older houses, where hidden damage and code upgrades are an issue. If the contractor’s quote for drying and cleaning is $6,900 but your insurer says $5,000, ask your contractor to communicate directly with the adjuster using detailed photos, moisture logs, and an itemized scope. Most reputable firms are used to this process and will submit supplements or negotiate on your behalf. In Pennsylvania, you must approve all work via a written contract, and you always have a three-business-day right to cancel if you change your mind.