water damage restoration costs in Morrisville — 2026
If you’re reading this in Morrisville, there’s a fair chance water is where it shouldn’t be right now. Bucks County’s aging housing stock, with 87.0% of homes built before 1980 and a 68.5% homeownership rate (U.S. Census Bureau, ACS 2024), means more cast iron, galvanized piping, and recurring leaks—especially in neighborhoods built out during the Levittown era. Old plumbing is a big reason interior water losses are so common here, driving up both emergency calls and the average repair bill.
Here’s what real numbers look like for water damage restoration in Morrisville. Costs swing widely—$1,300 for a small Category 1 loss, five digits for sewage or advanced mold. Finished basements, which are typical in Levittown-style homes, can push a midrange loss firmly into higher brackets.
| Service |
What it covers |
Typical duration |
Price range |
| Water extraction + emergency drying (Cat 1) |
extraction, air movers, LGR dehumidifiers, daily moisture monitoring |
3–5 days |
$1,300–$8,100 |
| Structural drying only (post-extraction) |
drying to standard after water is already out |
3–5 days |
$1,100–$7,600 |
| Mold remediation with containment |
containment, HEPA filtration, removal, antimicrobial, clearance test |
3–7 days |
$1,600–$11,500 |
| Sewage backup cleanup (Cat 3) |
biohazard protocol, disposal of porous materials, disinfection |
2–5 days |
$2,700–$13,000 |
| Emergency board-up / tarping |
stop further water entry, secure the structure |
same day |
$350–$900 |
Estimates for a typical Morrisville home. Category, affected area and how long the water sat move these figures more than anything else.
Finished basements and water damage in Morrisville
Morrisville’s homes, like much of lower Bucks County, tend to have full basements—a construction legacy of the 1950s–60s boom. Most of these basements are now finished, hiding plumbing, wiring, and wall cavities behind drywall and paneling. When water gets in, whether from a sump pump failure, foundation seepage or a pipe break, it’s not just a concrete surface getting wet—the problem quickly spreads behind walls and under flooring, often out of sight until trim starts swelling or you smell mildew.
Below-grade construction faces constant hydrostatic pressure, especially in our region where a 30-inch frost depth keeps the water table high. There’s no gravity drain—water lingers, especially in carpet padding, insulation, and base plates. If your sump pump fails (the most common cause here), and you don’t have a battery backup, groundwater will rise fast. A finished basement loss often doubles the scope and price compared to an unfinished space with the same amount of water, since every surface and concealed area is a potential trap for hidden moisture or mold growth.
Basement claims are rarely small: restoration means removing portions of drywall, base trim and sometimes flooring to dry what you can’t see. Skipping this step is inviting a return visit from mold within days, especially in our humid summer months.
Who pays for water damage in Morrisville
The line that costs Morrisville homeowners real money is simple: a burst pipe behind your wall? That’s usually covered by standard homeowners insurance. Water from the Delaware River or Neshaminy Creek breaching your basement? That’s a flood, and your regular policy won’t pay. Many only learn this after the water’s already in.
Gradual leaks—like a slow drip under your sink that rots away the cabinet—are typically denied because they’re considered maintenance issues, not sudden & accidental loss. Sewer backup coverage isn’t included by default here; you must purchase a separate rider, and it’s essential given Lower Bucks’ known inflow and infiltration problems. Coverage will also hinge on whether your insurer pays actual cash value (depreciated) or replacement cost (full repair) for damaged interiors.
A “scope of loss” is the itemized estimate that documents what was affected and what needs to be restored. If your contractor offers direct billing or an assignment of benefits, they’re asking for your permission to deal directly with the insurer—and to receive payment directly. This makes recovery simpler, but you surrender some control over claim negotiation.
Know your rights: Pennsylvania’s Home Improvement Consumer Protection Act requires a written contract if the job exceeds $500, with a three-business-day right of cancellation. Any offer to “waive your deductible” is illegal, and a red flag—you are on the hook for your share, and attempts to get around this put both you and the contractor at risk.
What proper drying actually looks like
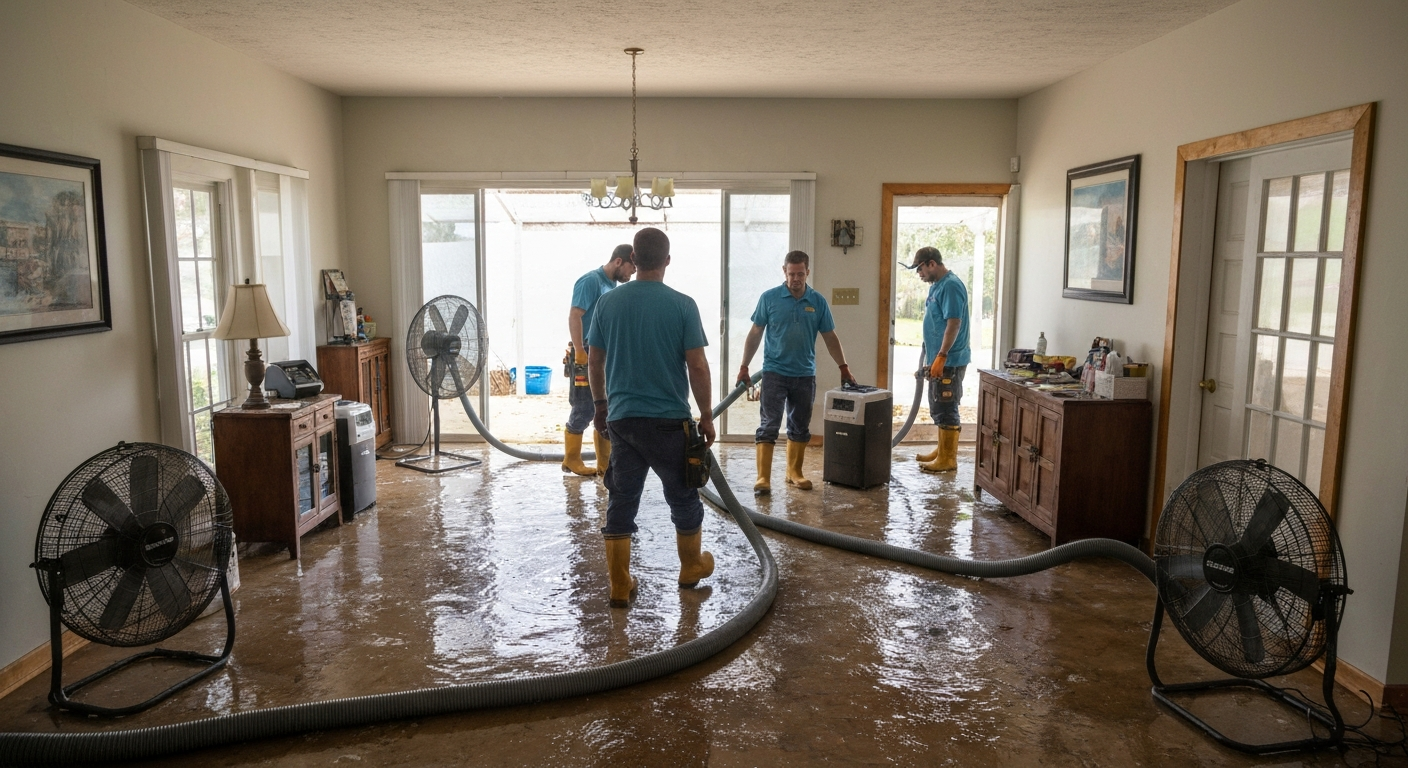
Competent restoration in Morrisville isn’t about throwing fans into a room—real structural drying is measured, recorded, and verified. Crews should always start with moisture mapping, using meters to document the extent of wet surfaces and set a baseline. Every day, those readings get logged; you should see a meter log or report, not promises. This tracking is critical in our region where humid summers and around 1,450 cooling degree days keep drying rates highly variable.
Air movers (which speed up evaporation) and LGR (low-grain refrigerant) dehumidifiers work in tandem, pulling water from both air and building materials. Equipment should run continuously, and you shouldn’t turn it off at night—even if the noise gets old. Players who cut corners here are gambling with your floors and walls; every overnight with equipment off extends the timeline and increases the cost.
Daily monitoring visits with recorded readings show progress toward a “drying goal”—a specific moisture percentage matched to unaffected areas or published standards, not a gut feeling. If your crew can’t show you a daily moisture log, they weren’t measuring, and neither you nor your insurer has proof the job finished right.
Morrisville's flood exposure and what it means for coverage
Morrisville’s proximity to the Delaware River—and, for parts of Bucks County, streams like Neshaminy and Pennypack Creek—means that some homes face a real threat from overbank and flash flooding. Flood zone maps determine who must carry flood insurance, but even homes outside high-risk zones have seen claims after upstream storms or blocked drains.
Standard homeowners insurance in Morrisville excludes almost all surface water intrusion—if water comes in from outside, you’ll need a separate flood policy (typically through the National Flood Insurance Program or a private carrier). That policy is purchased on its own, and most carry a 30-day waiting period before coverage begins, so you can’t pick it up when the forecast turns sour. It pays to check your property’s zone and buy early, especially given how similar a flooded home looks to a burst pipe loss. For your insurer, these two are processed completely separately—flood losses are a different claim, and the absence of coverage for outside water is rarely negotiable after the fact.
What to do right now
If you’re standing in water, act immediately. First, shut off your home’s main water supply—usually a lever or wheel at the point where water enters the house. Next, if you can do so safely (a dry floor, unbroken panel), switch off power at the affected circuit breaker to protect against shock. Don’t touch a wet or submerged panel; leave it alone.
Before you move anything, photograph every angle—walls, furniture, floors, even behind doors. Photos make claims smoother and help contractors scope the real loss. Move smaller items up off wet surfaces onto dry ground, but skip using a household vacuum on standing water—these aren’t built for gallons and lead to shocks or ruined equipment.
Contact your insurer—just as soon as, or even before, you call a restoration company. The order matters less than capturing everything with photos and notes. Don’t delay thinking things will improve overnight. Every hour matters: mold risk ramps up after 24-48 hours, and a cleanup that starts tonight averages $1,300–$8,100, while waiting can double the cost, especially when drywall and carpet pad turn to sponge. The single biggest mistake? Waiting until morning.
Regulation, certification and verification in Morrisville
Pennsylvania does not license restoration or mold contractors. Anyone can hand you a business card, so don’t trust labels alone. The IICRC S500 and S520 standards are what insurers expect; if you want a real professional, ask for the lead technician’s IICRC card at the door—qualified techs carry them and will show you without hesitation.
Permits aren’t needed for immediate extraction and drying in most Bucks County townships, but if the job requires opening walls to the studs and rebuilding framing, a building permit is likely needed. In Bensalem Township, for example, permits come into play when structural elements are changed, while other communities may have slightly different thresholds.
For any contract over $500, state law requires a written agreement with your contractor before work starts. Insist on written proof of valid Home Improvement Contractor (HIC) registration and verify the company’s workers’ compensation coverage using the state’s WCAIS system. This protects you if someone is hurt working in your home, and there’s no excuse for skipping written proof before starting extraction or demolition.
Frequently asked questions — water damage restoration in Morrisville
What does mold remediation cost in Morrisville?
Mold remediation prices in Morrisville usually fall between $1,600–$11,500, with a typical job landing around $6,500 for a finished basement or several rooms. The wide range relates to whether materials like drywall, insulation, or trim must be removed and how many square feet are affected. Older homes, common in this part of Bucks County, often hide moisture behind paneling or in wall cavities, so the price can jump if more removal is necessary for containment and clearance testing. It’s wise to insist on a written scope: Morrisville contractors should be familiar with the IICRC S520 standard, which most insurers require for mold claims, even though Pennsylvania has no licensing statute for mold.
What is an assignment of benefits and should I sign one?
In Morrisville, an assignment of benefits (often called an AOB) is a document that allows your restoration contractor to bill your insurer directly—and even negotiate parts of your claim on your behalf. It simplifies payment and speeds up repairs, but you give up control: the contractor works directly with the insurance company, not you. For some, that’s a relief in a crisis. For others, it means less say over repair decisions or settlement. Ensure the contract spells out exactly what you’re assigning; don’t sign a blank or open-ended AOB. Under the Home Improvement Consumer Protection Act, you have three business days to cancel a contract over $500. When in doubt, call your insurer or agent before signing.
Is basement flooding covered by insurance in Pennsylvania?
Generally, no—standard homeowners insurance in Pennsylvania, including Morrisville, excludes water that enters from outside, such as through basement windows or after heavy rain leads to surface flooding. You’d need a separate flood policy for that (with waiting periods before coverage starts). However, if your finished basement floods because a plumbing line bursts or a water heater fails, that’s usually a covered peril, and restoration for Category 1 water loss can run $1,300–$8,100. The key is the water’s source and how it entered the home. Always check the details of both your homeowners and flood policies to see what’s really covered.
Can hardwood floors be saved after flooding?
Sometimes, but it depends on how quickly you act in Morrisville’s climate. Engineered plank has a better survival rate than solid hardwood, but both can often be salvaged if drying begins within the first 24-48 hours. The cost for structural drying after water is removed lands between $1,100–$7,600. Successful restoration means using specialty drying mats and high-powered dehumidifiers—usual fans aren’t enough. If boards have started to cup or buckle, or if water sat so long that mold started growing beneath them, full replacement might be the only option. Don’t let anyone promise results without a moisture log and daily meter readings; that’s how you separate real restoration from guesswork.
How long until reconstruction starts?
In Morrisville, after mitigation, the reconstruction timeline depends on two things: how fast drying completes and whether a permit is needed for the repairs. Emergency drying typically finishes in 3–5 days (when meter readings hit the drying goal), while mold remediation may extend up to a week. You can’t safely rebuild until materials are confirmed dry—rushing in risks trapping moisture behind new finishes. If structural repairs are needed (wall framing, major drywall), expect to wait for a permit, especially in Bensalem Township. Minor non-structural repairs move faster. Most Morrisville firms aim for a quick handoff, but expect a brief gap between demo and rebuild. A common rule: restoration costs range from $1,100–$8,100 before reconstruction even begins.
Can I wait until morning to call?
That’s the single most expensive mistake in Morrisville, especially in a finished basement. The mold clock starts ticking at 24–48 hours, and every hour water sits multiplies the cost—what could have been a $1,300 loss easily crosses $6,500 if structures or contents require replacement and mold remediation. Crews here work 24/7 because water and bacteria don’t care about business hours. Photos, moving contents, and shutting off water are critical, but so is getting drying started soonest. Many insurance policies also require “reasonable efforts” to prevent further damage, so waiting may affect your claim down the line.
Do I need a permit for water damage repairs in Morrisville?
In most Bucks County township communities, including Morrisville, emergency water extraction and drying do not require a building permit if you’re just removing water, running fans, or pulling out carpet. If your loss involves replacing structural framing, drywall down to bare studs, or rebuilding load-bearing walls—as is sometimes the case in large finished basement floods—you may need a permit, especially if you’re in a municipality like Bensalem Township. Your restoration company should advise you before starting repairs. For mitigation-only jobs, though, don’t pay for a permit you don’t need. The typical mitigation bill: $1,300–$8,100.
What causes most water damage in Morrisville homes?
The top culprit in Morrisville is plumbing failure, driven by the area’s older 1950s–60s housing stock and the aging pipes that come with it. Sump pump failures—especially in finished basements—are the main reason for groundwater intruding after storms or snowmelt. Lower Bucks’ known sewer inflow issues can also trigger Category 3 backups, which require specialized cleanup costing $2,700–$13,000. While weather sometimes causes flood events from the Delaware River or Neshaminy Creek, these only account for a fraction of calls compared to everyday plumbing mishaps and pump breakdowns in basements.
Can I clean up water damage myself in Morrisville?
For very small, clean-water spills on hard floors, you might get away with DIY mopping and fans, but for anything more than a few gallons—especially in finished basements or if walls and insulation get wet—professional drying is strongly advised. Our humid summers here slow evaporation and boost mold risk. Once water wicks up drywall or into carpet pad, you’re into a scope where proper logging, air movers, and LGR dehumidifiers are needed—costing $1,300–$8,100 for typical jobs. If sewage or visible mold is involved, do not attempt on your own; the health risks and hidden moisture issues far outweigh any upfront savings.
Why is water damage priced per square foot?
Pricing per square foot in Morrisville reflects material, labor, and time—more surface area means more carpet, drywall, or flooring to remove and more air volume to dry. Larger spaces also need more equipment: each air mover or dehumidifier comes at a daily rental cost, and the more that’s wet, the more monitoring trips crews must make. The price spans from $1,300 for very local leaks to $8,100 or more for major basement events. Insurers and adjusters use these numbers to align with typical Bucks County restoration bills, but always check the full written scope and ensure you’re not being charged for spaces that aren’t truly affected.