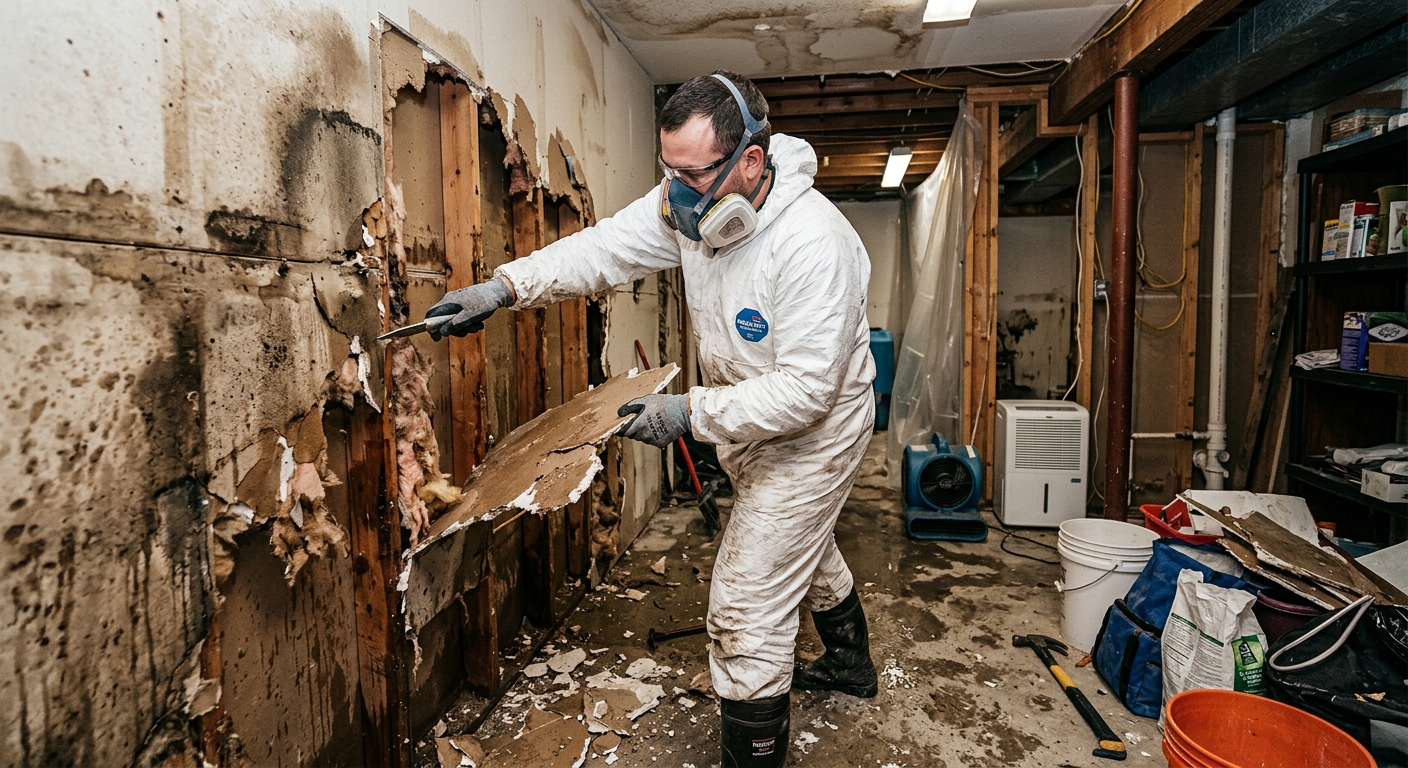
What water damage restoration costs in Taylor
If you’re reading this from Taylor, Pennsylvania and facing unexpected water damage, you’re probably wondering how much you’re on the hook for. Water losses in Taylor aren’t one-size-fits-all; costs are tied to how much of your house is finished versus bare, and how long the water sat hidden behind walls or beneath your floors. With most homes here built before 1980 (U.S. Census Bureau, ACS 2024) and more than half being single-family, a lot of jobs mean dealing with heavy plaster over wood lath, finished basements, and subfloors that keep moisture trapped—making thorough, expert drying critical and often pricier than a newer construction.
Here’s what real Taylor homeowners can expect to pay for restoration services:
| Service |
What it covers |
Typical duration |
Price range |
| Water extraction + emergency drying (Cat 1) |
extraction, air movers, LGR dehumidifiers, daily moisture monitoring |
3–5 days |
$1,100–$6,900 |
| Structural drying only (post-extraction) |
drying to standard after water is already out |
3–5 days |
$900–$6,400 |
| Mold remediation with containment |
containment, HEPA filtration, removal, antimicrobial, clearance test |
3–7 days |
$1,350–$9,600 |
| Sewage backup cleanup (Cat 3) |
biohazard protocol, disposal of porous materials, disinfection |
2–5 days |
$2,300–$11,000 |
| Emergency board-up / tarping |
stop further water entry, secure the structure |
same day |
$350–$900 |
Estimates for a typical Taylor home. Category, affected area and how long the water sat move these figures more than anything else.
What a Pennsylvania restoration contractor must actually hold
Pennsylvania does not issue any state license for water damage restoration or mold remediation contractors. Anyone can print a business card, so it’s smart to look beyond logos and ask for real credentials. While there’s no statewide restoration license, IICRC S500 and S520 are the standards insurance companies expect contractors to follow. It’s fair and wise to ask any crew chief for their IICRC certification card—this not only shows they’ve been tested on best practices, but also weeds out the fly-by-nights.
Contractors must hold Home Improvement Contractor registration from the Attorney General for work over $500. You can verify this online to make sure you’re dealing with a real, registry-listed business. For insurance, legitimate firms in Taylor carry both liability and workers’ compensation. Ask for the insurance certificate and check workers’ comp status via the state’s WCAIS system. Philadelphia and Pittsburgh have their own trade licensing, but not Taylor or the rest of Lackawanna County; rely on registration and insurance verification here.
Permits are only needed if the job goes beyond drying and moves into structural repairs—think rebuilding, not just removing wet carpet. Scranton, for example, requires permits for structural work, but routine mitigation like drying and minor surface work is typically exempt. Before any crew starts extracting or tearing out, insist on a detailed written contract describing the scope and price.
Basements: where most Taylor losses happen
In Taylor and the rest of Lackawanna County, nearly every home sits on a full basement—thanks to the region’s older construction and valley-grade lots. Most water damage claims in this area involve basements, where problems can go from mild to major fast. Below-grade space traps water, has no gravity drainage path, and is constantly exposed to ground pressure—especially during freeze-thaw cycles, with frost depths reaching 36 inches. When water gets in, it doesn’t leave easily.
Sump pump failure is easily the top single cause for water removal jobs. If your home relies on a sump pump and there’s no battery backup, a power outage during a storm (common here) means water rises quickly and keeps rising. If that basement is finished—and with so many Taylor homes updated post-World War II, plenty are—it can easily double the size and cost of a restoration, since every wall, carpet, and trim board that gets wet may need detailed work.
Finished basements hide water behind framing and drywall. Unlike in a concrete-only space, you rarely see the full extent of what’s wet, and hidden moisture against the foundation can linger, setting the stage for mold or damage to wood framing. Always insist on a thorough moisture check before agreeing to “just dry out” what you can see.
What proper drying actually looks like
Quality water damage restoration in Taylor is more than fans and hope. It starts with moisture mapping—measuring every wall, floor, and ceiling with meters to document what’s wet. Each reading should be logged daily, building a moisture history over the course of the job. Without that log, nobody can say when your home is truly dry or show an insurer proof that the work was done right.
Air movers get water out of surfaces by evaporation, while LGR dehumidifiers pull that airborne moisture out so it doesn’t condense elsewhere. In the Scranton area’s humid summers and cool basement temps, equipment may need to run for three to five days or more—stopping it at night just slows the process and can encourage mold. A competent crew visits at least once per day, records fresh meter readings, and updates you on progress. The true drying goal is not “it feels dry” but reaching a specified, measured moisture content that matches local building materials in dry conditions.
The practical test in Taylor: ask to see the daily moisture log at any point. If there isn’t one, you have a right to question whether drying is actually happening. Our climate—with cold winters, moderate heating needs (6,100 heating degree days), and 850 cooling degree days—means that outdoor air might not always help; proper dehumidification indoors matters way more than opening windows.
Outside water, inside water
A major factor in Taylor is the Lackawanna River, which means that some homes face both standard internal leaks and true flood exposure. The difference is critical: water from a burst pipe inside your house is a covered peril on almost every policy, while “flood”—water that enters from outside, especially when the river overflows or surface water travels over ground—needs specific, separately purchased flood insurance.
If your address is in a mapped flood zone, your mortgage likely required you to buy a flood policy, which always comes with its own deductibles and payout limits. Even if you’re outside those high-risk zones, flood insurance takes 30 days to take effect, so you can’t add it when a nor’easter is already in the forecast or after there’s water in your basement. Many Taylor homes are near enough to the river or sit at the bottom of a slope, making this distinction real every storm season.
To a homeowner, flood and indoor pipe breaks look nearly the same: wet floors, damaged drywall, ruined possessions. But adjusters treat them as night and day—floods get handled under FEMA’s rules or private flood policies and are just not covered by your homeowner’s insurer. Know your risk before the water rises.
The first hour: what to do before anyone arrives
Before you call anyone to the house, here’s what to do when water hits your Taylor home:
- Turn off the water at the main shut-off if the source is plumbing-related.
- If you can reach your breaker panel safely and it’s dry, shut off power to just the affected area.
- Take photos of every room, surface, and detail before you move anything—insurers will want proof of the “before.”
- Move items off wet floors; prioritize electronics, rugs, and anything irreplaceable, but don’t stack wet things on dry furniture.
- Never use a household vacuum—especially a shop vac—on standing water. You risk shock, shorts, or worse.
Call your insurance company at the same time or even before the restoration contractor. It matters less which comes first than making sure everything is documented before clean-up. Avoid the common mistake of waiting until morning—every hour water sits means more damage under floors or behind walls, and more risk mold remediation is needed. The difference between a $1,100–$6,900 drying job and a $1,350–$9,600 mold remediation is often just those hours you waited. Get the clock started: document, call, and plan to act now rather than later.
Hiring under pressure in Taylor
In Taylor and Lackawanna County, the reality is you might start making calls before you’ve even finished mopping up. The moderate suburban market here means several firms are available locally, and metro Scranton-based crews can get to your door within an hour or two. But when many homes are hit at once, you may get called back by companies bringing crews in from outside the immediate area. Don’t assume the first available is the best fit—act fast, but confirm the basics.
On the phone: confirm that (1) the company holds valid Home Improvement Contractor registration, (2) carries liability and workers’ compensation insurance, and (3) can name their IICRC-certified lead and provide credentials onsite. That’s all it takes to filter out most fly-by-nights.
Before the first equipment comes in, have these three in hand: a contract laying out the scope and price, a copy of the company’s insurance certificate, and written confirmation of your three-day right to cancel under state law.
- Home Improvement Contractor registration number (verify online yourself)
- Written, signed contract spelling out scope, price, and terms
- Proof of general liability insurance
- Workers’ compensation certificate (check via WCAIS if in doubt)
- Lead technician’s IICRC certification card, shown on arrival
- Moisture mapping plan to show where they’ll measure and monitor
- Daily job log promised in writing
- No vague or blank work authorizations—everything itemized up front
- Copy of your three-day right of cancellation notice (standard in Pennsylvania)
- Clarity about if/how any charges may increase depending on findings
Watch out for pressure tactics—crews who start unloading equipment before you sign, “blank scope” or open-ended work authorizations, or asking you to sign insurance claim rights over to them. Insist on reviewing every document before the job starts; if they get defensive, move on. There’s enough contractor density in Taylor that you don’t have to jump at the first truck through your street.
Frequently asked questions — water damage restoration in Taylor
Why did the crew cut my drywall two feet up?
To stop mold and speed drying, professionals in Taylor typically cut drywall two feet above visible water damage—this is called a “flood cut.” Local homes, many built before 1980, often have moisture trapped both inside the wall cavities and spreading laterally behind lath or insulation. A two-foot cut guarantees easy access to check framing and ensure air movement inside walls. If you leave wet drywall or insulation sealed up, mold can start fast and repairs become much more expensive—jumping from a $1,100–$6,900 job to a full $1,350–$9,600 mold remediation.
What does structural drying cost if I extracted the water myself?
If you’ve already removed the standing water from your Taylor home and just need professional drying (no extraction), you’ll pay for “structural drying only.” In Lackawanna County, this typically runs between $900–$6,400, depending mostly on how much area is affected and how long the water sat before you got fans running. Professional drying covers powerful air movers, LGR dehumidifiers, daily monitoring, and moisture readings—critical in Taylor’s old plaster or finished basement construction, where moisture likes to hide. You’ll still need a pro to confirm it’s truly dry before repairs begin.
How long before mold starts growing?
Once water hits drywall, plaster, or wood framing in a Taylor home, mold can begin to grow in as little as 24 to 48 hours—sometimes sooner if the basement is humid or the weather is warm. Delaying professional drying is one of the most expensive mistakes; a response within the first day can mean the difference between a $1,100–$6,900 drying job and a much bigger $1,350–$9,600 remediation if mold takes hold. Taylor’s older homes with finished basements are especially vulnerable because walls or subfloors can hide damp spots.
Why does plaster take longer to dry than drywall?
Plaster walls, common in Taylor homes built before 1980, are denser and more absorbent than modern drywall. They soak up more water and dry out more slowly. Plaster is usually laid over wood lath, so moisture can also be trapped between the two layers, needing careful monitoring. As a result, it’s not uncommon for a water loss in a plaster-walled home to come closer to the high end of the drying range ($6,400 for structural drying), simply because equipment must stay running longer and more checks are needed to hit a safe moisture level.
Do older Taylor homes need different treatment?
Absolutely. With 76.0% of Taylor’s homes built before 1980, restoration crews see a lot of unique problems: plaster and lath walls, finished basements, and subfloors that don’t drain or dry like new construction. These homes often trap water for days behind surfaces, so expect detailed moisture mapping, more careful demolition, and longer drying times. A “standard” newer home might dry for $2,700, while an older Taylor home often ends up at the upper end of the $6,400 price band simply due to hidden moisture and extra work involved in careful restoration.
Does Pennsylvania license mold remediation contractors?
Pennsylvania does not have a state-issued mold remediation license. That means anyone can say they do mold work in Taylor—so you need to look for a contractor that follows IICRC S520, the national standard that insurance adjusters and real experts use. Insist on an IICRC-certified technician leading the job, and demand daily moisture logs and a final clearance test, especially for jobs in the $1,350–$9,600 range. The lack of licensing makes it even more important to check credentials, references, and certifications yourself.
Do I need separate flood insurance in Taylor?
Yes. Standard homeowner’s insurance in Taylor, as in the rest of Pennsylvania, excludes flooding from the outside—including water from the Lackawanna River or surface runoff down your street. If your property is in or near a mapped flood zone, you need a separate flood insurance policy. These take 30 days before they kick in, so you can’t buy a policy last minute. If you suffer a covered flood loss without insurance, a full cleanup ranges from $2,300–$11,000 out of pocket.
Is bleach effective against mold?
Bleach may wipe away mold’s surface color, but it doesn’t solve the problem. In Taylor homes—especially with plaster or finished basements—mold roots often grow into or behind surfaces, where bleach has no real effect and can worsen conditions by adding moisture. Real mold remediation involves HEPA filtration, containment, physical removal, antimicrobial treatment, and a clearance test, priced from $1,350–$9,600 locally. Don’t waste money on bleach; you’ll likely end up doing the proper fix later anyway.
Is emergency after-hours service more expensive in Taylor?
After-hours water damage calls (evenings, nights, weekends) generally come with higher minimum service charges in Taylor, as in much of Pennsylvania. While the price bands—$1,100–$6,900 for extraction and drying—stay the same, the lower end is less common on nights and holidays simply due to overtime rates. Still, waiting until morning can cost more in extra damage than you save, especially in finished basements where hidden moisture multiplies both the scope and the price of the restoration.
What is an assignment of benefits and should I sign one?
An “assignment of benefits” (AOB) form allows your contractor to file, negotiate, and receive payment directly from your insurer for repairs on your Taylor home. AOBs can speed up the process but often shift control over the job’s scope and cost from you to the contractor. In Pennsylvania, never sign anything blank or unclear; always make sure the AOB spells out exactly what work is covered and for what price. If a job will be more than $500, require a signed contract under the Home Improvement Consumer Protection Act and read cancellation terms carefully.